



Europe Is Bringing Financial and Company Data Together
Companies and financial market participants across the European Union already disclose large amounts of regulated information. Today, that information sits across different countries, registers, supervisory authorities and other data sources.
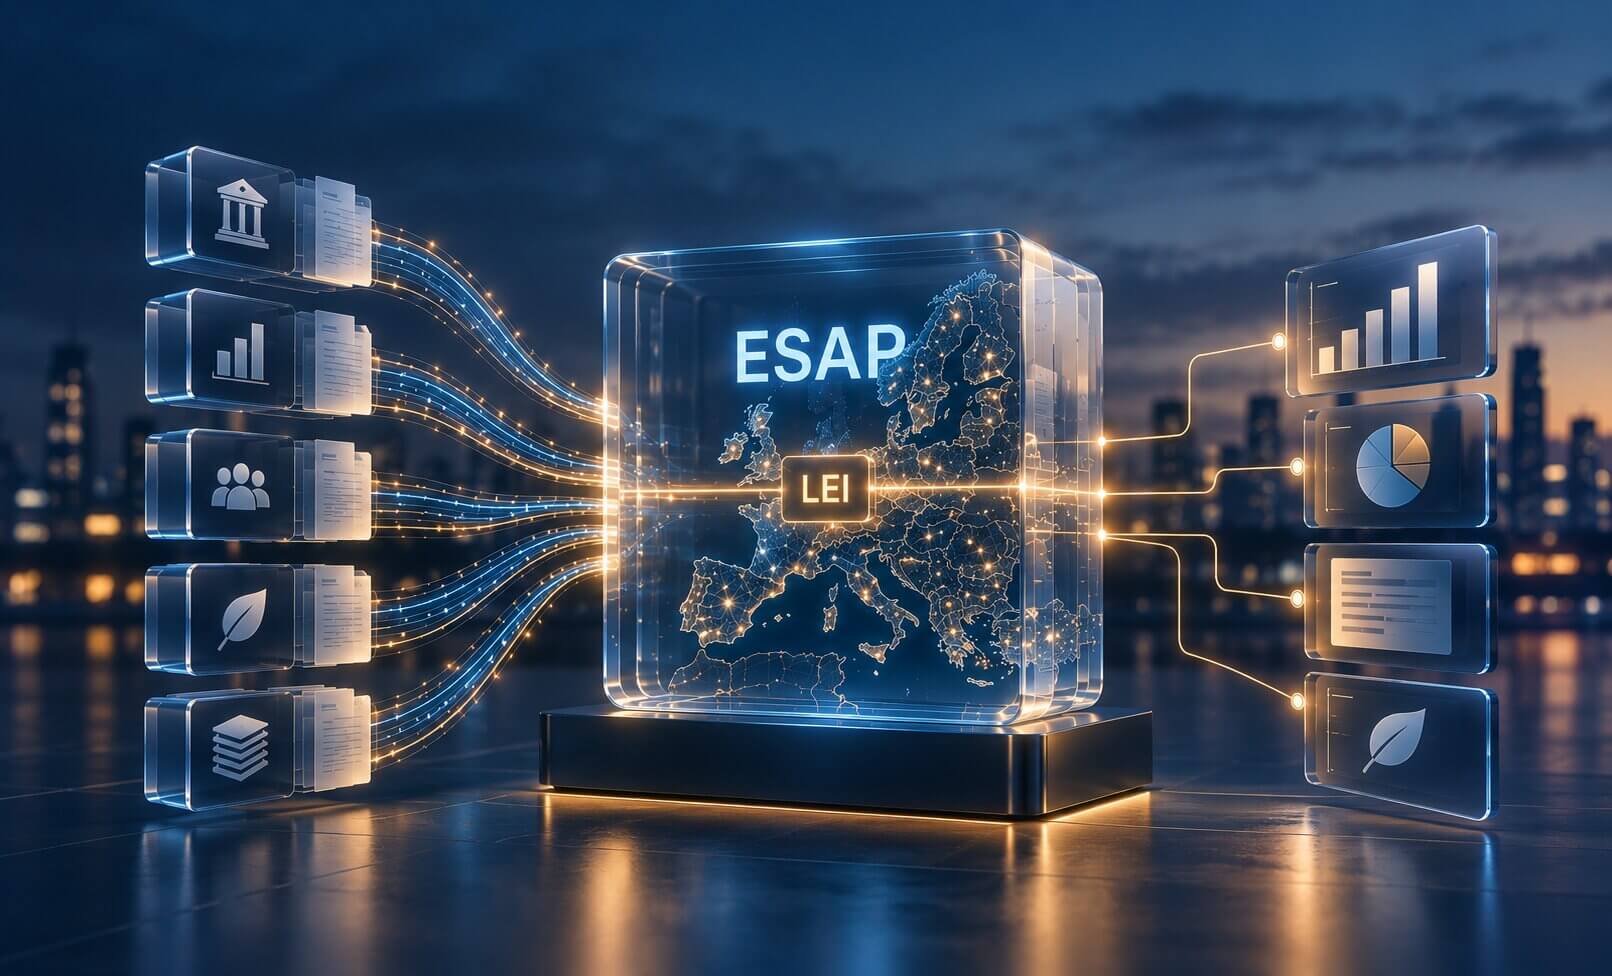
The European Single Access Point, or ESAP, aims to bring it together.
The European Securities and Markets Authority (ESMA) is developing ESAP as a central platform for financial, capital markets and sustainability-related information published across the EU.
It is not a new European business register. Instead, ESAP will bring together information that companies and other market participants already disclose under various EU rules.
The first phase of data collection started on 10 July 2026. According to ESMA’s official timeline, the public portal will become available in July 2027.
The idea goes beyond putting documents in one place. For the system to work, data from different countries and sources needs to be standardized, machine-readable and reliably linked to the correct legal entity.
That makes the Legal Entity Identifier, or LEI – the globally standardized identifier for legal entities – an important part of the picture.
ESAP Will Expand Step by Step
ESMA and national authorities will expand ESAP in several phases, adding new categories of information and market participants over time.
The first phase started in July 2026 and covers information under three important pieces of EU legislation.
The Transparency Directive governs, among other things, periodic and ongoing disclosures by issuers whose securities trade on regulated markets.
The Prospectus Regulation sets out the information companies must disclose when they offer securities to the public or seek admission to trading on a regulated market.
The Short Selling Regulation covers disclosure requirements for certain short positions and related market information.
ESMA launched data collection for this first phase on 10 July 2026. The collected information should become publicly accessible through ESAP in July 2027.
More financial market data will follow
The next major expansion starts in January 2028, when ESAP will cover a much broader range of financial market information.
This includes UCITS (Undertakings for Collective Investment in Transferable Securities) – investment funds offered to the public under a common EU regulatory framework – and their management companies.
ESAP will also cover credit rating agencies, which assess the credit risk of companies, governments and financial instruments, as well as benchmark administrators, which manage interest rates, indices and other financial benchmarks used to price financial instruments and contracts.
Another category covers providers of PEPPs (Pan-European Personal Pension Products). A PEPP is an EU-wide voluntary personal pension product designed for use across different Member States.
Sustainability-related information will also enter the system. This includes disclosures by financial market participants and financial advisers under the SFDR (Sustainable Finance Disclosure Regulation), the EU framework for sustainability-related disclosures in the financial sector.
ESMA’s timeline includes a further Phase 2bis in January 2029, alongside an assessment of how ESAP is working.
If the third phase receives confirmation, it will start in January 2030. Among other areas, it will include information published under MiFID II (Markets in Financial Instruments Directive II) and MiFIR (Markets in Financial Instruments Regulation) by investment firms, trading venues and other financial market participants.
MiFID II and MiFIR form a major part of the EU securities markets framework, covering investment services, securities trading and transaction transparency. We explain the role of the LEI under these rules separately in LEI Code and MiFID II: No LEI, No Trade.
Over time, ESAP will therefore become a common public access point for a significant amount of European financial market information.
The More Data We Connect, the More Important It Is to Know Who It Belongs To
Putting millions of documents and data records into one system creates a practical problem: how do you know which legal entity a particular piece of information actually belongs to?
A company name is not always enough.
Companies can write their names in different ways and can change their names or legal forms. Different countries use different registration numbers, while completely unrelated companies can have identical or very similar names.
An LEI gives a legal entity a standardized, globally usable 20-character identifier.
In the context of ESAP, the basic logic is simple:
legal entity → LEI → information about the entity → ESAP
ESAP brings the information together, while the LEI helps establish who that information belongs to.
This makes the LEI more than another field in a regulatory report. It can act as a common reference point when information from different countries, authorities and systems needs to be connected to the same legal entity.
The same principle sits at the heart of the wider Global LEI System. We explain how GLEIF, LEI issuers, regulators and other participants fit together in How the Global LEI Ecosystem Works.
The LEI Is Built into the ESAP Architecture
ESAP rules do not use the LEI in exactly the same way in every case.
For some market participants, ESAP-related legislation explicitly requires an LEI. This applies, for example, to certain securities issuers, UCITS funds, credit rating agencies, benchmark administrators and PEPP providers.
Under Regulation (EU) 2023/2869, PEPP providers must obtain an LEI and include it in the metadata accompanying information submitted to ESAP. The framework takes a similar approach for several other types of legal entities.
For other categories of information, the rules use the LEI where one is available.
The technical rules are also explicit about what qualifies as an LEI. Under Commission Implementing Regulation (EU) 2025/1338, where an LEI is required for ESAP purposes, it must comply with the ISO 17442 standard and be included in the Global Legal Entity Identifier Foundation (GLEIF) database.
The bigger trend goes beyond ESAP
The individual requirements are only part of the story. ESAP is also another example of the LEI becoming more deeply embedded in Europe’s financial, legal and reporting infrastructure.
Financial institutions and regulators already use the LEI for transaction reporting and market participant identification. Its role has expanded into securities markets, funds, payments, regulatory reporting and other financial processes. We look at this wider development in How LEI Works in Practice in the EU.
ESAP adds another use: connecting a legal entity with structured information published about it.
As European financial data moves towards machine-readable formats, that connection becomes increasingly useful. Data from different countries and systems can only be compared and processed reliably if systems know which legal entity it belongs to.
A standardized identifier solves that problem. Increasingly, the LEI provides that link.
The Role of the LEI Is Changing with Europe’s Financial Data Architecture
One of the main reasons for creating the LEI was the need to identify counterparties to financial transactions consistently across borders.
The 2008 financial crisis exposed a major weakness in the global financial system. Regulators and market participants lacked a common way to identify legal entities involved in transactions and understand how risks moved between companies and markets.
The same principle now has a much wider use.
It is no longer only about identifying who made a transaction. Regulators and financial systems also need to know which legal entity financial data, reports and regulatory disclosures belong to, and whether information held in different databases refers to the same entity.
The LEI data model can also go beyond identifying the entity itself. For example, LEI Level 2 data provides a standardized way to report certain accounting consolidation relationships between legal entities.
ESAP fits naturally into this development. As more European financial information becomes standardized and machine-readable, an identifier that works across countries, languages and local registration systems becomes more useful.
From 2030, ESAP Will Not Be Limited to Mandatory Disclosures
A particularly interesting change is scheduled for 10 January 2030.
From that date, the ESAP Regulation (Regulation (EU) 2023/2859) allows EU entities to voluntarily submit certain financial, capital markets, sustainability-related and other information relevant to economic activities.
Until then, ESAP’s main role is to make information that regulation already requires easier to access. Voluntary submissions could broaden that role considerably.
A company may actually want to be visible in ESAP.
For smaller companies in particular, standardized and easily accessible information could improve visibility among investors and other financial market participants. The ESAP Regulation itself identifies greater visibility for small and medium-sized enterprises and improved access to capital as reasons for enabling voluntary submissions.
There is an interesting LEI angle here as well. If companies voluntarily add information to a common European machine-readable system, reliable identification becomes just as important as it is for mandatory disclosures.
Voluntary Today, Standard Tomorrow?
No regulation currently says that ESAP will become a mandatory database for every European company.
Still, the direction of travel is worth watching.
European financial markets have moved for years towards greater transparency, standardized reporting and machine-readable data. At the same time, the scope of the LEI has gradually expanded. We look at some of the current developments in LEI Requirements in 2026: What Is Changing, and Who It Affects.
There is a familiar pattern. A standardized identifier starts in a specific regulatory area. Other systems and market participants begin to use it. Some rules initially use the LEI only where one already exists, while others make it a mandatory part of the regulatory process.
Whether ESAP follows the same path over the longer term remains to be seen.
What we can see already is the underlying need. Regulators want better visibility of market participants, greater transparency and data that systems can compare and process automatically. All of that becomes much harder without a reliable way to identify legal entities across borders and databases.
From that perspective, it is reasonable to expect the LEI to play a growing role in Europe’s financial data infrastructure. The same direction can also be seen in initiatives such as the European Business Wallet, where reliable digital identification of legal entities is becoming increasingly important.
ESAP Is Part of a Bigger Shift
ESAP matters on its own, but from an LEI perspective the broader trend is just as interesting.
Europe is moving towards a more connected, standardized and machine-readable financial data environment. Information from different countries and systems needs to be comparable and reliably linked to the right company or organization.
That makes legal entity identity part of the infrastructure.
The LEI fits naturally into this model: one legal entity, one internationally standardized identifier, and a way to connect that identity with information held across different systems.
ESAP is not the beginning of this development, and it is unlikely to be the end.
It is another step towards a European financial system where the LEI increasingly acts as a common identity layer for legal entities.
Need an LEI?
If your company needs an LEI, you can register an LEI online with LEI System. The application takes only a few minutes to complete.